US Single-Family Starts Rebound as Asia–US Container Rates Jump
August US single-family starts rose 7.6% to 918,000. Frame Hai Phong public bars at or above Drewry’s Shanghai coast figures. SBV reference 25,637.
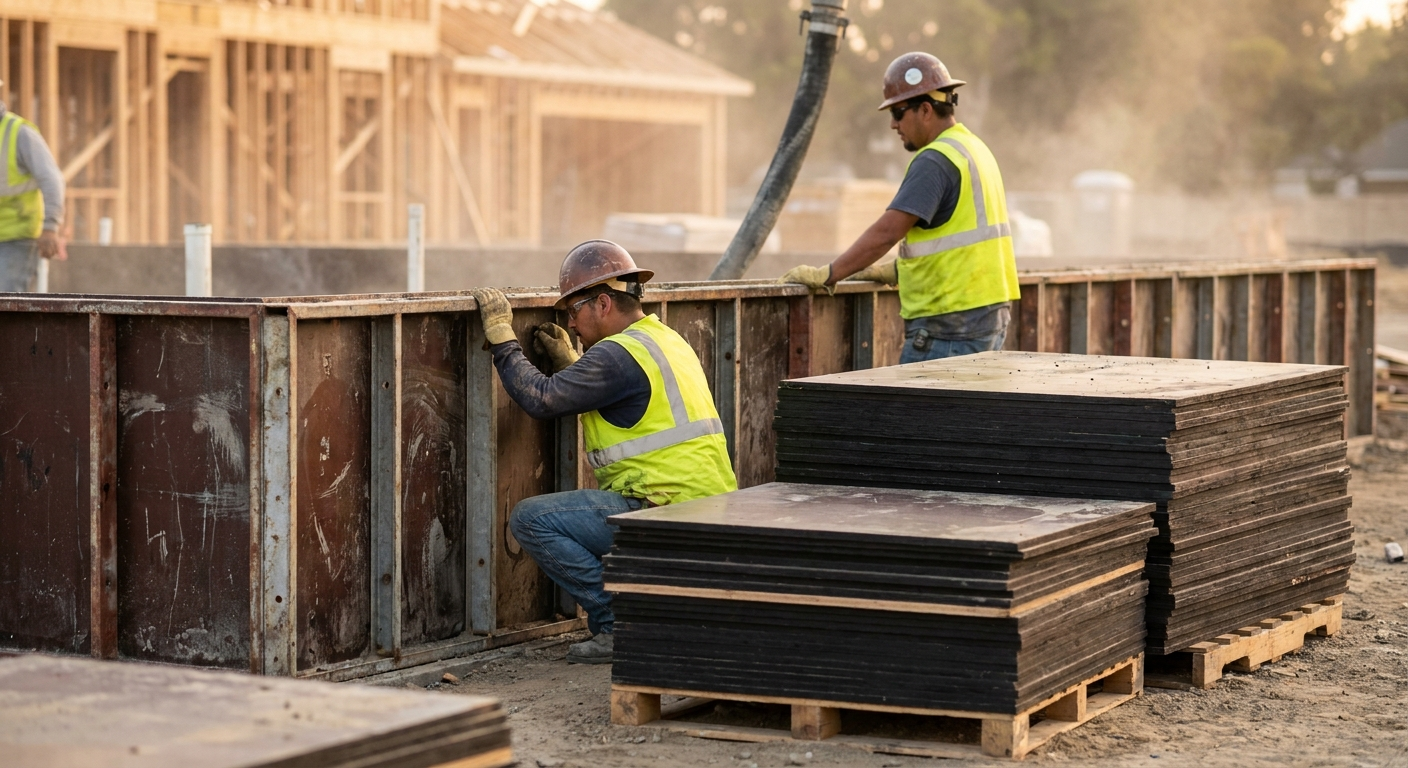
US single-family housing starts rebounded in August even as the overall starts print cooled. The Census Bureau, reported by Reuters on 17 September, put privately owned starts at a seasonally adjusted annual rate of 1,275,000 — down 2.6% from July and 1.2% year over year. Inside that headline, single-family starts rose 7.6% to 918,000 (+5.2% YoY). Units in buildings with five or more apartments fell 22.5% to 344,000. For a formwork buyer, the single-family leg is the pour signal that fills residential gang schedules; the multi-family drop is the part of the print that still looks soft.
Permits did not keep the same pace. Overall permits fell 2.7% to 1,394,000. Single-family permits eased 1.8% to 878,000. Mortgage rates near 6.76% on the Freddie Mac survey and a Federal Reserve funds target of 3.75–4.00% sit behind a cooler NAHB builder sentiment reading — one-year low on the wire reports. Starts up, permits a touch softer: plan inventory against the pours already in motion, not against a blank cheque for Q4 volume.
Our 14 September brief led on cancelled Asia–US sailings. This week the demand print is the lead. Freight still matters — Transpacific container rates jumped on the Drewry coast legs — but it rides second to the housing rebound for anyone buying film-faced plywood into North American residential pours.
Single-family starts matter more than the overall print
A seasonally adjusted starts rate is an annualised estimate, not a count of slabs poured last month. Still, a 7.6% month-on-month lift in single-family starts is the clearest August signal for residential formwork demand. Multi-family at −22.5% keeps the overall starts figure from looking like a broad boom. That split is useful on a purchase order: residential wall and slab programmes that run on single-family plots need panel weeks booked now, while large multi-family towers can wait for clearer permit momentum.
Quiet permits do not cancel the sheets already on a pour calendar. They do argue against stretching inventory as if August starts will automatically repeat every month. Hold what covers the next six to eight pour weeks. Leave speculative Q1 volume until permits and sentiment stop drifting lower.
Asia–US container rates jump from Hai Phong framing
Drewry’s World Container Index stood at $4,500 per 40ft on 17 September, up about 1% from $4,476 the week before, per Daily Cargo News on 18 September. The Shanghai–Los Angeles leg rose 5% to $7,712. Shanghai–New York rose 7% to $10,394. Shanghai–Rotterdam fell 9% to $3,626 and Shanghai–Genoa fell 5% to $4,016. Drewry’s WCI is a Shanghai-composite benchmark. For a northern Vietnam mill, treat public Hai Phong posting guidance for a 40HC to the US West Coast as at or above $7,712, and to the US East Coast as at or above $10,394. Soft whispers under those bars are not a planning figure.
Carriers announced nine Transpacific cancelled sailings for next week, up from eight. A cancelled sailing — also called a blank sailing — means the line drops that voyage; the ship does not run that week. It is not a vessel leaving empty. Four Asia–Europe cancelled sailings were announced, up from one. Shanghai average vessel wait rose to 78 hours in Week 37 from 65 hours in Week 36. Pre–Golden Week stuffing and capacity management are the usual seasonal pressure. Suez return traffic is still pressing Asia–Europe space, with Red Sea risk noted on the same Drewry window.
From our mill desk, we would lock the Hai Phong load week against those US coast bars before treating a flat World Container Index average as a reason to wait. Europe’s cheaper Rotterdam and Genoa figures only help if the container stays on the week you bought.
Panama Canal stress hits East Coast service planning
Reuters reported on 17 September that Panama Canal daily transits are being cut toward 32–34 in September, with auction premiums extreme on energy cargoes and container holiday rush plus Middle East rerouting adding stress. Asia–US East Coast services depend on that canal. A rolled East Coast container does not only pay a higher ocean line; it can miss the pour week the sheet was bought for. Price the USEC public bar at or above $10,394 and keep a West Coast backup path on the PO when the job can accept either coast discharge.
SBV reference climbs. Dollar FOB still rules the sheet.
The State Bank of Vietnam set the central rate at 25,637 VND per USD on 18 September, up five dong from the prior day, VietnamPlus reported. Vietcombank’s buy/sell quotes sat at 25,820 / 26,200. Most Vietnam mill FOB contracts invoice in dollars. A buyer converting euros, Australian dollars, or won into that invoice feels the week’s move even when the panel list holds. Write FX as its own landed-cost line next to ocean and origin wait.
Phenolic Class 3 / EN 636-3 product such as Pro Form still belongs on exterior or long wet-storage pours. Form Extra remains a higher-melamine-content MUF panel in the EN 636-2 envelope and is not Class 3. A firmer single-family starts print does not change the bond class on the RFQ.
What to do this week
Treat the August single-family starts rebound as the demand lead for residential formwork arrivals over the next fortnight. Frame Hai Phong public guidance at or above $7,712 West Coast and $10,394 East Coast on the 17 September Drewry Shanghai coast figures. Keep cancelled sailings and Panama transit cuts as secondary schedule risks on the freight file, not as the headline story. Convert FOB against the 25,637 central rate and the bank sell side you actually pay.
Keep film-faced and structural formwork lines on clean purchase orders so freight, FX, and glue class stay readable to the yard that will strip the sheet. For Q4 residential programmes that already have pour dates, book mill week and vessel week together rather than waiting for permits to catch the starts print.
About Vinawood
Vinawood is a Vietnamese plywood manufacturer established in 1992. The mill ships more than 5,000 containers a year to 55+ export countries across Asia, the Americas, Europe, the Middle East, Africa and Australia, with film-faced and formwork panels built on a documented production process and individual sheet inspection. Core certifications include ISO 9001, FSC-COC, PEFC, EN 13986 CE marking, and EPA TSCA Title VI for US-bound orders. Wood is plantation-grown. For Q4 and Q1 formwork enquiries, request a quote.
Category
market-insights
Related Markets
Related Countries
Related Products
▶Sources & References (5)
- US single-family housing starts rebound in August; building permits fall — Reuters (2026-09-17)
- Monthly New Residential Construction — U.S. Census Bureau (2026-09)
- World Container Index – 17 September 2026 — Daily Cargo News / Drewry (2026-09-17)
- Reference exchange rate continues to climb on September 18 — VietnamPlus / SBV (2026-09-18)
- Panama Canal stress shows real shipping squeeze may still be ahead — Reuters (2026-09-17)